30-Day Financial Prep Before a Collaborative Divorce Intake
Financial preparation for a CollaborativeDivorce intake means gathering and organizing income, account, debt, and property records before the first Collaborative Divorce meeting, so both spouses start have the same information.
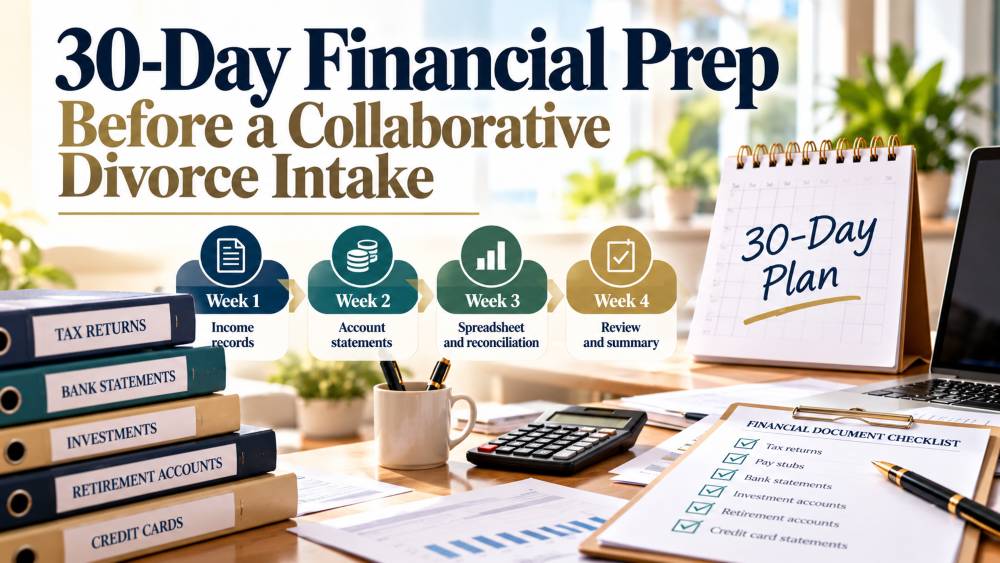
A solid plan, such as a 30-day plan, helps keep the information gathering and meeting preparation manageable. Carolann Mazza, P.A. (Collaborative Solutions), a non-litigation family law firm in Fort Lauderdale, Florida, uses those records to build each Collaborative Divorce settlement plan.
Key Takeaways
- Florida’s Form 12.932 checklist, which tracks Family Law Rule of Procedure 12.285, lists 3 years of personal tax returns among required disclosure documents in filed cases.
- The same checklist lists 6 months of pay stubs and 12 months of checking, brokerage, and retirement statements.
- The Form 12.932 checklist requires a 24-month lookback for credit card statements and loan applications.
- Form 12.932 instructions state that the financial affidavit cannot be waived, while other disclosure items may be modified by agreement or court order.
Missing records stall every process, and, in particular, the first Collaborative meeting in a Collaborative Divorce. Carolann Mazza, P.A. provides a document checklist, so spouses can schedule an intake consultation fully prepared.
Why Does Financial Prep Matter in a Collaborative Divorce Case?
Collaborative Divorce depends on voluntary financial disclosure, so preparation determines how quickly the team can move from gathering information to discussing options.
Rule 4-1.19 of the Rules Regulating The Florida Bar directs Collaborative attorneys to assess whether a client is likely to cooperate in voluntary disclosure before the process begins.
Two disclosure frameworks apply at different stages:
- Before any court filing: Disclosure happens voluntarily within the Collaborative process, and the team sets its scope.
- After a dissolution case is filed: Rule 12.285 mandatory disclosure applies. Exceptions include simplified dissolution and cases where a respondent served by constructive service does not answer. Spouses may modify most items by agreement, but not the financial affidavit.
The Rule 12.285 list below is therefore a recommended preparation benchmark for all divorce processes.
In the firm’s Collaborative cases, the team works from a document checklist and disclosure plan, then builds a joint financial snapshot of income, expenses, assets, and debts.
Each spouse also shares goals and interests for resolution before negotiation begins, which keeps meetings focused on decisions rather than missing paperwork.
Which Financial Documents Should Be Gathered Before a Collaborative Intake?
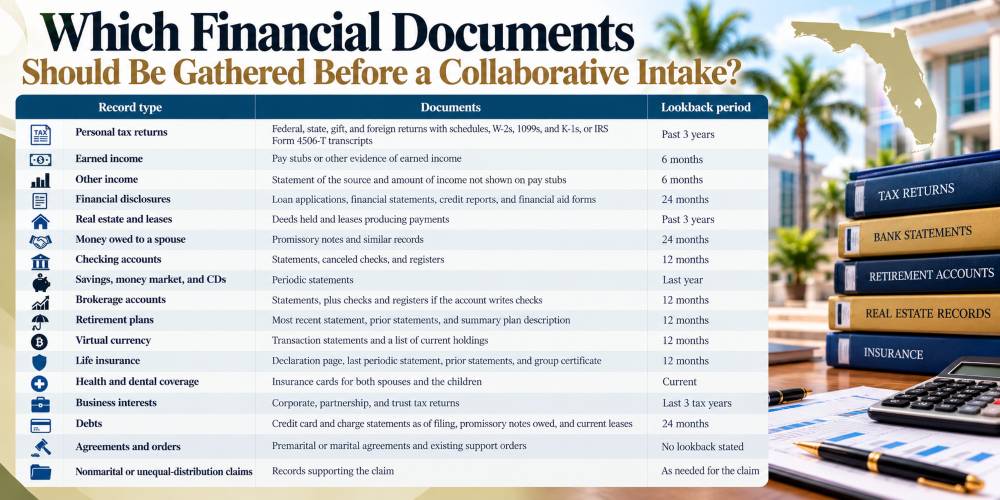
The Form 12.932 Certificate of Compliance, published by the Florida Courts, itemizes the Rule 12.285 documents and lookback periods that apply once a case is filed.
Using that list at the intake stage matches what a court expects when the settlement and Florida financial affidavits are eventually filed.
| Record type | Documents | Lookback period |
| Personal tax returns | Federal, state, gift, and foreign returns with schedules, W-2s, 1099s, and K-1s, or IRS Form 4506-T transcripts | Past 3 years |
| Earned income | Pay stubs or other evidence of earned income | 6 months |
| Other income | Statement of the source and amount of income not shown on pay stubs | 6 months |
| Financial disclosures | Loan applications, financial statements, credit reports, and financial aid forms | 24 months |
| Real estate and leases | Deeds held and leases producing payments | Past 3 years |
| Money owed to a spouse | Promissory notes and similar records | 24 months |
| Checking accounts | Statements, canceled checks, and registers | 12 months |
| Savings, money market, and CDs | Periodic statements | Last year |
| Brokerage accounts | Statements, plus checks and registers if the account writes checks | 12 months |
| Retirement plans | Most recent statement, prior statements, and summary plan description | 12 months |
| Virtual currency | Transaction statements and a list of current holdings | 12 months |
| Life insurance | Declaration page, last periodic statement, prior statements, and group certificate | 12 months |
| Health and dental coverage | Insurance cards for both spouses and the children | Current |
| Business interests | Corporate, partnership, and trust tax returns | Last 3 tax years |
| Debts | Credit card and charge statements as of filing, promissory notes owed, and current leases | 24 months |
| Agreements and orders | Premarital or marital agreements and existing support orders | No lookback stated |
| Nonmarital or unequal-distribution claims | Records supporting the claim | As needed for the claim |
A spouse claiming an asset or debt is nonmarital should gather records tracing it back to its acquisition.
Section 61.075, Florida Statutes, treats premarital property and inheritances differently from marital assets. Complex holdings, such as business interests or retirement plans, usually require the longest lead time.
If you’re ready to get started, call us now!
How Should Financial Records Be Organized and Shared Securely?
Organization should make every record findable in under a minute, and sharing should protect account numbers and other identifiers. A master folder, consistent file names, and one summary spreadsheet accomplish both goals without special software.
- Master folder: One digital folder or paper binder with a subfolder for each record type
- File names: Date, institution, and account type, such as “2026-08-Bank-Checking-Statement.pdf”
- Account spreadsheet: One row per account with type, institution, last 4 digits, balance, monthly payment, and owner, such as “Checking | Bank A | 1234 | $3,200 | none | joint”
- Missing-document tracker: A separate tab listing each missing record, the request date, and the expected arrival date
- Privacy: Account numbers shortened to the last 4 digits in summaries, consistent with the identifier limits in Florida Rule of General Practice and Judicial Administration 2.425 for court filings
- Secure sharing: Records sent only through the method the collaborative attorney designates, rather than unencrypted email or shared family devices
A spouse who cannot access an account held or controlled by the other spouse should list the account on the gap list and raise it with their attorney.
Logging into the other spouse’s accounts without authorization is never part of preparation, and the Collaborative disclosure process is the proper route. Spouses who have never reviewed household finances together may find that talking about money goes more smoothly once both see the same spreadsheet.
What Should Happen in Each Week of the 30-Day Plan?
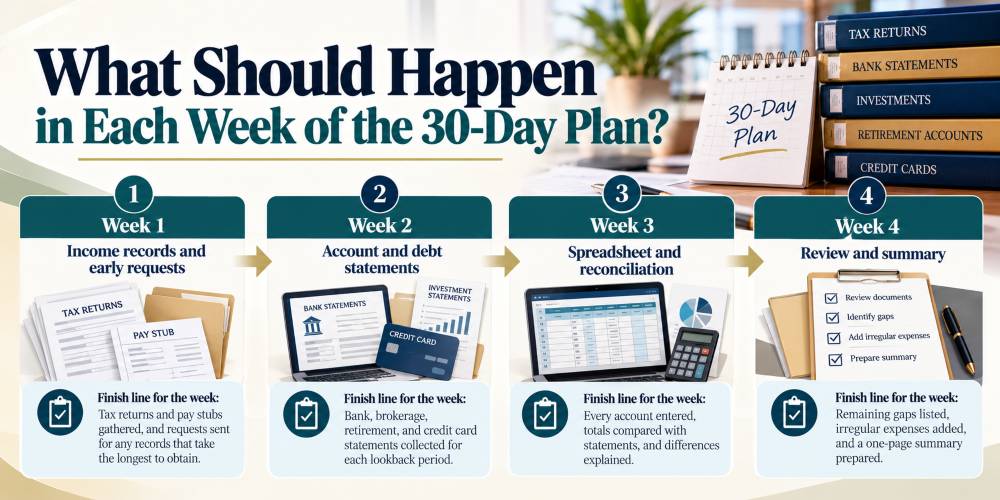
The 30-day plan is a recommended organizing framework, not a legal deadline, and complex finances may need more time. The order of the information moves from income to accounts to analysis to review, so gaps surface while you still have time to fill them.
| Week | Focus | Finish line for the week |
| Week 1 | Income records and early requests | Tax returns and pay stubs gathered, and requests sent for any records that take the longest to obtain |
| Week 2 | Account and debt statements | Bank, brokerage, retirement, and credit card statements collected for each lookback period |
| Week 3 | Spreadsheet and reconciliation | Every account entered, totals compared with statements, and differences explained |
| Week 4 | Review and summary | Remaining gaps listed, irregular expenses added, and a one-page summary prepared |
Requesting slow records in week 1, such as retirement plan descriptions, business returns, or IRS transcripts, prevents week 4 from becoming a waiting period.
During week 3, recurring transfers to an unfamiliar account often reveal a forgotten account, a review step that fits into preparing for Collaborative divorce more broadly.
How Can Missing Financial Records Be Replaced Quickly?
You can replace several common records through official channels within days. Requesting copies early prevents the first meeting from turning into a list of follow-up tasks.
- Tax returns: The IRS Get Transcript service provides transcripts through an online IRS account. Mailed transcripts arrive within 5 to 10 calendar days after a request at 800-908-9946.
- Credit history: The Federal Trade Commission confirms that Equifax, Experian, and TransUnion each provide a free credit report once a week through AnnualCreditReport.com.
- Bank and card statements: Most institutions let account holders download past statements or request older ones from customer service.
- Retirement plans: Plan administrators can send the summary plan description and recent statements on request.
A credit report can reveal cards and loans one spouse never saw. Form 12.932 also lists credit reports among the disclosures prepared within the prior 24 months.
Which Financial Prep Mistakes Slow a Collaborative Divorce?
Common delays come from incomplete statements, unexplained differences between records, and expenses that do not appear every month. Each problem can pause analysis until the missing explanation arrives.
Incomplete or Partial Statements
Statements missing a first or last page leave gaps in beginning and ending balances. Every account held during the lookback period belongs in the file, along with the mandatory financial disclosure records that tie each balance to a statement.
Differences That Need an Explanation
Pay stubs and bank deposits rarely match exactly, for three common reasons:
- Gross pay includes taxes, retirement contributions, and insurance premiums withheld before deposit.
- Paychecks may split across accounts.
- Pay dates may fall in a different statement month.
Reconciliation means each difference has an explanation, not that every number is identical.
Missing Irregular Expenses
Monthly budgets often omit costs that arrive once or twice a year, such as auto insurance premiums, property taxes, vehicle registration, and summer childcare. Reviewing 12 months of account activity brings these costs into the expense list, which keeps divorce financial planning realistic.
How Does Intake Prep Feed the Financial Affidavit and Settlement?
The gathered records become the source material for each spouse’s sworn financial affidavit and for the settlement’s support and property terms.
The Form 12.932 instructions direct spouses with individual gross income under $50,000 a year to the short-form affidavit, Form 12.902(b), and higher earners to the long form, Form 12.902(c).
After disclosure in a filed case, the Form 12.932 instructions impose a continuing duty to share documents that change a spouse’s financial status, so the spreadsheet should stay current.
Carolann Mazza, Esq., Florida Supreme Court Certified Family Mediator, has practiced Florida family law since 2001 and resolves divorces through Collaborative Divorce, mediation, and settlement processes rather than litigation.
Collaborative teams vary in structure, and a financial neutral joins only when the case calls for one.
Common reasons to add a neutral include differences between the spouses in experience with or understanding of the couple’s full financial picture, business or equity compensation, commission compensation, multiple retirement plans, or disputed nonmarital claims. The neutral organizes records into shared reports but does not replace a CPA or business valuation expert.
Contact Us Today For An Appointment
Frequently Asked Questions
What documents should be brought to a first Collaborative Divorce meeting?
This varies by case, though in general it is helpful if the spouses have provided recent tax returns, pay stubs, account statements, debt statements, deeds, insurance records, and any premarital agreement, plus a summary spreadsheet to the financial professional. Documents and information should be supplemented as necessary or it becomes available.
How far back should bank statements go for a Florida divorce?
Florida’s Form 12.932 checklist calls for 12 months of checking statements, with canceled checks and registers, and the last year of savings, money market, and certificate of deposit statements. Those periods apply to mandatory disclosure once you file a dissolution case.
How many pay stubs are needed for a Collaborative Divorce?
This varies by case. In general, the Form 12.932 checklist calls for 6 months of pay stubs or other evidence of earned income in a filed case. Spouses with bonuses, commissions, or self-employment income should also prepare a statement of other income sources covering that same period.
Is the 30-day prep schedule a legal requirement?
No. The 30-day schedule is an organizing framework, and Rule 12.285’s 45-day deadline applies only if the case has been filed in court. Depending upon the issues involved, gathering business records, retirement plans, or missing records may take more time to collect.
What if one spouse cannot access an account before the intake?
That spouse should list the account on the gap list and tell their attorney or the financial professional rather than attempt unauthorized access. Collaborative divorce depends on voluntary disclosure, so the account holder is expected to produce those statements through the Collaborative team.
Can a spreadsheet replace the actual financial documents?
No. A spreadsheet summarizes accounts and balances, but the Collaborative team still needs the underlying statements, returns, and pay records to verify each figure. The spreadsheet serves as a roadmap, showing the Collaborative team where each supporting document fits.
How should sensitive financial records be shared?
Spouses should share records only through the method agreed to and and shorten account numbers to the last 4 digits in summaries. Unencrypted email and shared family devices create real privacy risks for tax returns, statements, and identification numbers.
When does a Collaborative Divorce need a financial neutral?
A financial neutral helps most when the case involves differences between the spouses in experience with or understanding of the couple’s full financial picture, a business, equity or commission pay, several retirement plans, or disputed nonmarital assets. The neutral works equally for both spouses and does not replace a CPA or business valuation expert.
Bottom Line
Financial prep for a Collaborative case is important to keep the case flowing and to make sure the relevant information is available to both spouses. The Rule 12.285 document list is a good guide for financial organization.
A 30-day plan with early requests, a reconciliation step, and secure sharing leaves the team ready to begin analysis, though the timeline to settlement still depends on each case.
Prepared spouses spend meetings on decisions. Carolann Mazza, P.A. keeps families out of court, so spouses can book a confidential consultation with records ready.
About the Author
Carolann Mazza
Florida Family Law Attorney (The Florida Bar, admitted 2001) · Florida Supreme Court Certified Family Mediator (certified 2011, No. 25475F) · Super Lawyers, Family Law, 2022–2026
Carolann Mazza is the founder of Carolann Mazza, P.A., a non-litigation family law firm she opened in Fort Lauderdale in 2003. Practicing family law in Florida since 2001 and admitted to the State Bar of Texas in 1997, she resolves divorce and family conflicts exclusively through Collaborative Divorce, mediation, and out-of-court settlement — keeping families out of court while preserving relationships, dignity, and children’s wellbeing. She serves Broward, Palm Beach, and Miami-Dade counties.